New: z3x Talent Pool gives companies access to experienced FinTech specialists. Learn more

Merchant Account Opening

Finding a payment provider is easy. Finding one that understands your business, accepts its risk profile and offers workable terms can be much harder. z3x helps companies secure the right payment acceptance setup by identifying suitable acquirers and PSPs, preparing merchant account applications, supporting underwriting and coordinating onboarding. We stay involved from the first assessment to payment launch.


A merchant account that fits your business, not just an application form

An unsuccessful application, an unsuitable payment provider or unexpectedly restrictive terms can delay revenue, disrupt expansion and put existing payment flows at risk. The challenge is often not a lack of payment providers, but a mismatch between their underwriting criteria and the merchant’s business model.

We work on the merchant’s side to evaluate options, explain requirements and manage a practical route to payment acceptance. Depending on the setup, this may involve a direct acquiring relationship, a PSP or a payment facilitator model rather than a standalone merchant account. The objective is a sustainable payment solution with clear responsibilities, realistic costs and operational support.

What We Offer

Four areas of support, from finding the right provider to completing a workable onboarding process.

Merchant Account Opening & Provider Selection

We assess your business model, transaction profile, target markets and payment requirements, then identify relevant acquirers and payment service providers. We compare coverage, onboarding criteria, settlement models, contract terms, fees and technical capabilities. Our job is to help you select a credible route to payment acceptance rather than submit applications indiscriminately.

High-Risk & Complex Merchant Support

Some lawful business models face enhanced scrutiny because of chargebacks, delivery timing, subscriptions, industry classification, geography or past processing history. We help merchants understand potential risk concerns, document their operating model transparently and approach providers whose policies may support the activity. We never promise approval or support hiding the true nature of a business.

International & Cross-Border Merchant Accounts

Entering new markets can require a different acquiring structure, local payment methods, new currencies, appropriate settlement arrangements or additional entities. We help evaluate international merchant account options, country coverage, cross-border restrictions, FX economics and operational dependencies. The objective is to align payment acceptance with the commercial expansion plan.

Merchant Onboarding & Underwriting Support

We help prepare application materials, explain KYB and beneficial ownership requirements, coordinate responses to provider questions and address gaps in website information, fulfilment policies, refunds or payment history. We also support discussions about reserves, chargebacks, settlement schedules, risk controls and contract terms. Final underwriting decisions remain entirely with the provider.

How We Work

A structured, hands-on process designed to reduce avoidable friction without bypassing payment provider controls.

1

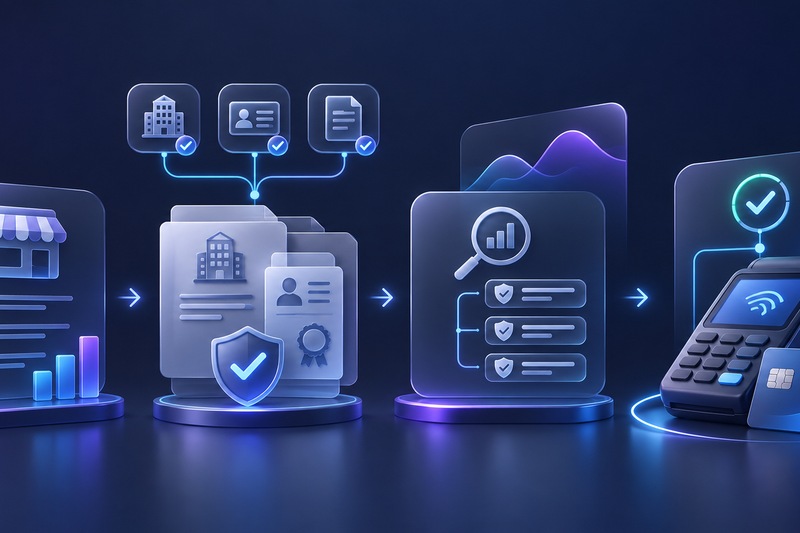
1. Understand Your Business

We review what you sell, how customers pay, where you operate, expected volumes, average transaction values, delivery or subscription models and current payment challenges. We identify any relevant documentation, policy or operational gaps before contacting providers.

2

2. Match You With Suitable Providers

We define selection criteria and evaluate relevant acquirers, PSPs or payment facilitator arrangements. We compare business-model acceptance, target-market coverage, payment methods, pricing, settlement, operational conditions and integration needs, then recommend a short list.

3

3. Prepare & Manage Onboarding

We support the application, help organise accurate supporting documents and coordinate commercial and operational questions. Where appropriate, we participate in provider discussions and help the merchant respond consistently to risk, underwriting and compliance requests.

4

4. Support Launch & Next Steps

Once a provider approves the application, we help coordinate the handover to integration, testing and operational setup. We review payment acceptance, reporting, settlement and support arrangements, and identify further optimisation opportunities as volumes or markets develop.

Trusted across the financial services industry

A declined merchant account application is a signal to investigate, not a reason to apply everywhere

A declined merchant account application is a signal to investigate, not a reason to apply everywhere

A provider can decline a merchant for many reasons: restricted sectors, unsuitable geography, incomplete ownership information, high chargeback exposure, delivery or refund practices, or a risk profile outside its appetite. Submitting the same application to more providers without understanding the issue rarely improves the underlying case.

We help distinguish problems that can be addressed through better documentation and controls from restrictions that are fundamental to a provider’s policy or the law. Where legitimate options exist, we identify the appropriate payment acceptance model and prepare a clearer, consistent application. Approval is never guaranteed, but the process can be more informed and efficient.

The right merchant account is also about what happens after approval

The right merchant account is also about what happens after approval

Merchant account opening is only the beginning. Funding delays, rolling reserves, chargebacks, payout currencies, account restrictions and a poorly matched integration can all affect cash flow and customer experience. A low transaction fee can become expensive if the overall operating model does not fit the business.

We evaluate practical conditions alongside the commercial offer: settlement timing, reserve policies, refund handling, reporting, fraud tools, support arrangements and the ability to expand. Our focus is not simply getting an application accepted, but helping establish payment acceptance that the business can operate and scale.

Who We Help

We focus on businesses where acquiring requirements are more complex than a standard self-service signup.

E-commerce & Digital Merchants

Online retailers with significant volumes, international customers, complex fulfilment or a need for tailored payment acceptance terms.

SaaS & Subscription Businesses

Companies with recurring billing, trial-to-paid journeys, recurring disputes or international subscription revenue.

Marketplaces & Platforms

Platforms that need to distinguish merchant-of-record responsibilities, submerchant onboarding, split payments and settlement arrangements.

Cross-Border Businesses

Merchants operating across countries, legal entities or currencies and requiring an acquiring model that fits their expansion strategy.

Merchants With Previous PSP Rejections

Legitimate businesses seeking to understand past declines, address documented weaknesses and evaluate suitable providers.

Established Merchants Reconsidering Acquiring

Businesses moving beyond standard PSP pricing or seeking an additional acquiring relationship for resilience and growth.

Why Work With z3x?

We approach merchant account opening from the perspective of payment operations, acquiring economics, product design and implementation — not as a generic referral directory. Our role is to represent the merchant’s business requirements, challenge unsuitable assumptions and coordinate practical next steps with providers.

We can also support adjacent work after onboarding: payment cost optimisation, online payment integrations, payment orchestration and ongoing payments expertise. That means a merchant account decision can be made in the context of the complete payment infrastructure, not in isolation.

What Our Clients Say

The z3x team demonstrated a high level of professionalism and an excellent understanding of the specifics of the FinTech and e-commerce market. The audit, detailed analysis of the competitive environment, and local customer expectations provided us with valuable data that really supported the decision-making process and planning for the launch of new services. We appreciate the strategic approach, timeliness, and quality of the materials prepared. The cooperation went smoothly and fully met our expectations.

Working with the z3x team on auditing our processes proved to be very valuable. We received a detailed analysis of existing solutions, reliable research, and specific recommendations for changes and improvements. The team demonstrated extensive knowledge of the industry and the ability to combine business and technological perspectives. The entire process ran smoothly, and the materials prepared provided a solid basis for further optimization activities.

Working with the z3x team helped us define the direction of our product development in a new customer segment. The market analyses, customer segmentation, and recommended solutions provided us with concrete data and insights that directly influenced our product decisions and future development plan. What I particularly value about z3x is their extensive knowledge of the payments market, their practical approach, and their strong commitment to the project. I wholeheartedly recommend working with this team to anyone looking for a partner who combines expert knowledge of FinTech with the ability to translate that knowledge into concrete and actionable recommendations.

Collaboration with Z3X Tech-Care Group helped us structure and redesign selected processes within our digital environment. Through targeted automation and operational flow optimization, we achieved improved operational efficiency and enhanced customer conversion performance.

Z3X are experts who advised us on chatbots, automation, and integrations. Thanks to their support, we eliminated many manual processes, accelerated company processes, and gained ready-to-use solutions. With their expert knowledge in AI and automation, the team led by Jakub Smeda and Karol Zielinski is highly recommended to all managers who need competent technology consulting.

Collaborating on the implementation of the debt collection game (memo) was an interesting and inspiring project for us. The solution stood out for its unconventional approach to customer communication, effectively increasing response rates in the initial phase of the campaign and demonstrating the potential of modern tools in the field of collections. We particularly appreciate the team’s flexibility and openness to tailoring the solution to our needs. The project served as a valuable complement to our standard strategies and provided us with many valuable insights that we are using to further develop our processes.

The z3x team provided comprehensive support throughout the design and development process of our new mobile application - from the initial concept, through product strategy development, to the final implementation. The collaboration covered both the technological and business aspects, with every stage carried out with great attention to detail and quality. The team demonstrated an excellent understanding of our needs, high flexibility, and the ability to efficiently address emerging challenges. The implementation of payments was just one of many well-executed components in this complex project.

Collaboration with Z3X Tech-Care Group helped us structure and clarify the direction of our next steps in preparing the organization to work with AI.

Frequently asked questions

A merchant account is commonly used to describe the acquiring arrangement that enables a business to accept card payments and receive settlement. In a traditional setup, a merchant may have a direct acquiring relationship and a dedicated merchant identifier. Other models, including payment facilitators or aggregated PSP arrangements, may onboard the business as a sponsored or submerchant. We help determine which setup fits your business, rather than assuming a dedicated merchant account is always required.

No. Every acquirer or PSP applies its own onboarding, compliance and underwriting criteria, and only the provider can make an approval decision. We assess potential fit, identify documentation gaps and help you approach appropriate providers with accurate information. If a business model is prohibited or does not meet eligibility criteria, we will not suggest hiding or misrepresenting it to obtain approval.

We can review the circumstances and help identify likely issues, subject to the information available. These may involve chargeback levels, business-model restrictions, ownership details, location, fulfilment, risk controls or processing history. We then assess whether the concerns can legitimately be addressed and whether another provider may be suitable. We cannot reverse a provider’s decision or guarantee that a replacement provider will accept the business.

We can assess more complex profiles, including lawful businesses with elevated underwriting risk, cross-border sales, recurring billing or international entities. The availability of providers depends on the specific activity, jurisdictions, ownership structure, transaction profile and applicable rules. Some business types may be restricted across the available provider market. We only pursue transparent, compliant options and confirm the provider’s willingness to review the case before treating it as a viable route.

Requirements vary by provider and business model, but commonly include company registration documents, ownership and beneficial-owner information, identity verification, expected volumes and a clear description of products or services. Providers may also request websites, terms and conditions, refund and delivery policies, financial statements, processing history or chargeback data. Some merchants need additional licensing or sector-specific evidence. We help prepare an accurate, consistent application package based on the selected provider’s actual requirements.

Timing depends on the provider, business complexity, completeness of documents and the scope of underwriting. Standard cases may move quickly, while more complex or cross-border applications can require additional reviews. We do not promise a fixed approval time because the provider controls the decision and its review process. After approval, we can support integration coordination, settlement setup, operational handover and subsequent payment optimisation.

Latest Reports and Articles - FinTech Strategy & Product Development

What is PCI Compliance?
FinTech

What is PCI Compliance?

PCI compliance is one of the core security requirements for companies that accept, process, store or otherwise handle payment card data. For merchants...

Sept. 15, 2026, 8:55 a.m.
Karol Zielinski
453

Need a Merchant Account That Actually Fits Your Business?

Tell us what your business does, where it operates and what payment acceptance problem you need to solve. We will help assess the options and define a practical next step.

Do not submit cardholder data, banking credentials or sensitive identity documents through the initial enquiry form.


Let's Change the Game Together

Like what you have seen? Let’s get started. Just fill in a few details and we will get in touch as soon as possible.

Please, enter your first name!
Please, enter your last name!
Please, enter your first name!
Please, enter your company!
Please, enter your message!
Top